
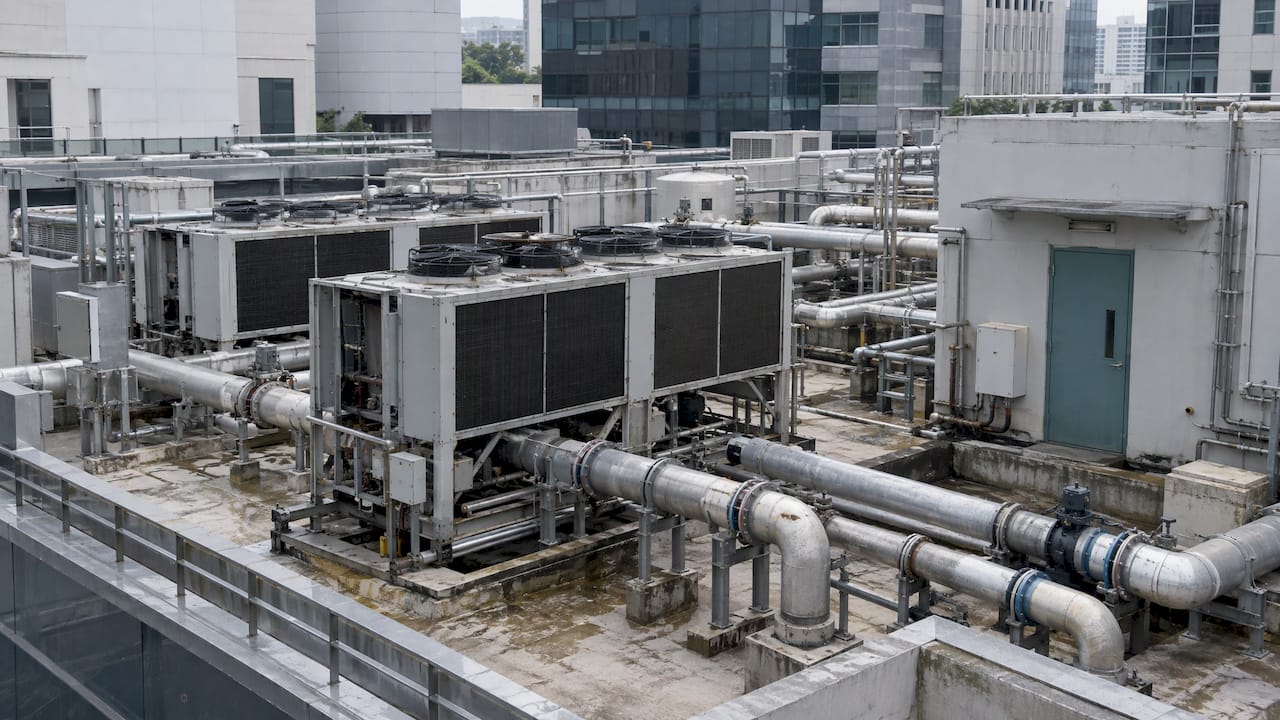
Life cycle cost analysis (LCCA) is the method of comparing design, system and material options by their total cost over a defined study period, not by construction cost alone. For a Singapore developer, building owner or investor, a sound LCCA identifies the option with the lowest discounted cost across construction, operation, maintenance, replacement and decommissioning. It is most useful when it is applied during design, while the alternatives are still open. Aman Engineering Consultancy supports this analysis through its Value Engineering, Quantity Surveying and Feasibility Studies services.
TL;DR
- LCCA compares alternatives on discounted total cost over a fixed study period. It covers initial capital, operating, maintenance and replacement costs, plus end-of-life costs where relevant.
- The Building and Construction Authority (BCA) used a 30-year study period, a 5% discount rate and 1.5% annual escalation in its Green Mark consultancy study. These are workable reference assumptions, not fixed rules.
- Operating costs can exceed the initial construction cost over the life of a building, so first-cost comparisons alone are incomplete.
- Results depend on the assumptions. Sensitivity testing on discount rate, study period and cost escalation is part of a defensible analysis.
- The analysis carries most weight at concept and design stage, when a change of system or material costs least.
Table of Contents
- What the terms mean for buildings
- Why first cost is an incomplete measure
- The stages a life cycle cost analysis covers
- How to calculate a building LCCA, step by step
- Comparing materials, systems and design alternatives
- Singapore guidance and tools
- Handling uncertainty in the estimate
- Where the analysis fits in the project programme
- Our perspective
- Commissioning a life cycle cost analysis
- FAQ
- Sources
What the terms mean for buildings
The three terms in common use are life cycle cost analysis, life cycle costing (LCC) and whole life cost analysis (WLC). According to the RICS professional standard on life cycle costing, LCC assesses the relevant construction, maintenance, operation and disposal costs over a defined period. WLC has a broader scope and can include client and user costs, income and external costs. Some publications use the terms interchangeably. An academic review of the field notes that ISO 15686 distinguishes LCC from WLC, while ambiguity remains over intangible, external and environmental costs.
In practice, a Singapore project team should state in the brief which definition applies. If the analysis covers only costs borne by the owner, it is an LCC. If it also prices user costs, income or externalities such as carbon, it is a WLC. Either is valid, provided the boundary is written down before any figures are compiled.
Why first cost is an incomplete measure
The BCA explains that developers should consider first costs and long-term running costs such as utilities, operations and maintenance, which can run for 30 years or more, and that operating expenditure (OPEX) can outstrip initial capital expenditure (CAPEX) as a building ages. The same BCA article describes LCCA as the tool for finding a project’s true cost, and states that applying it early in design allows developers to select the option that is most cost-effective to build, operate, maintain and decommission.
A Singapore-specific data point comes from a Bond University study of 44 non-residential buildings constructed between 1978 and 2013. It found an annualized average LCC of S$222.03/m², of which construction averaged S$91.85/m² and operation S$130.18/m². Operation accounted for the larger share. The same study reports that each one-level increase in Green Mark standard raised annualized LCC by S$47.81/m² and construction costs by S$25.37/m², without a significant effect on operational costs. These figures describe that sample and period. They indicate the scale of the trade-off and are not a substitute for project-specific estimates.

The stages a life cycle cost analysis covers
The RICS guidance identifies the main stages of a building’s life as design and construction, operation, maintenance, and end-of-life disposal or decommissioning. A comprehensive analysis covers each of them:
| Stage | Typical cost items | Typical Singapore considerations |
|---|---|---|
| Design and construction | Professional fees, construction, fit-out, authority submissions | Statutory approvals and certification costs are part of initial capital |
| Operation | Electricity, water, cooling, cleaning, security | Air-conditioning loads dominate in most commercial buildings |
| Maintenance | Planned servicing, inspections, minor repairs | Statutory periodic inspections recur on a fixed cycle |
| Replacement | Chillers, lifts, pumps, façade components, roofing | Replacement timing depends on component design life |
| End of life | Demolition, decommissioning, or residual value | Residual value may offset part of the cost |
Recurring statutory items belong in the maintenance line. Owners of qualifying buildings are subject to the Periodic Structural Inspection and Periodic Façade Inspection regimes, and any rectification works that follow form part of the life cycle profile. A proactive maintenance strategy changes the timing and size of those later costs, which is why the maintenance assumptions deserve as much attention as the capital figures.
How to calculate a building LCCA, step by step
The method is consistent across published guidance: define the problem, set the assumptions, compile costs, discount them to a present value and compare. The steps below follow that sequence.
- Define the objective and the alternatives. State the decision: for example, two façade systems, two chiller plants, or a retained structure against a rebuild. Include a base case, usually the lowest first-cost option, so that every alternative is measured against it.
- Fix the study period. The BCA’s consultancy study of 25 non-residential and 15 residential projects used a 30-year study period. Choose a period that reflects the holding period or the design life of the main systems, and apply the same period to every alternative.
- Set the discount rate and escalation. The same BCA study used net present value (NPV) at a 5% discount rate, with 1.5% annual escalation. NPV converts future costs into today’s money so that costs incurred in different years can be added together.
- Compile the costs. The BCA study included initial capital, operating, maintenance and replacement costs. Quantity surveying input and manufacturer data should support each line. Where the system is new to the team, a design-stage cost plan reduces the reliance on assumptions.
- Compute the NPV for each alternative. Discount each year’s cost at the chosen rate and sum the results with the initial capital.
- Compare and test. The BCA study normalised NPV savings by gross floor area (GFA) to compare projects of different sizes. Rank the alternatives by lowest NPV, then test how stable the ranking is when assumptions change.
A worked example
The following is an illustrative calculation with invented figures, intended to show the mechanics. Two cladding options are compared over 30 years at a 5% discount rate. Costs are held constant in real terms, so escalation is excluded for simplicity.
| Option A (lower first cost) | Option B (higher first cost) | |
|---|---|---|
| Initial cost | S$1,000,000 | S$1,150,000 |
| Annual maintenance | S$40,000 | S$25,000 |
| Present value of 30 years of maintenance | S$614,880 | S$384,300 |
| Total NPV | S$1,614,880 | S$1,534,300 |
The present value of a level annual cost over 30 years at 5% is the annual amount multiplied by 15.372. Option B costs S$150,000 more at handover but has a lower total NPV by S$80,580. The additional S$150,000 is recovered through a S$15,000 annual saving, which on a simple basis takes ten years to repay. Under this analysis, Option B is the preferred choice.
Comparing materials, systems and design alternatives
The RICS guidance describes LCC as a decision-support tool for option appraisal and value-for-money decisions, comparing alternatives with different initial and later operational costs, such as insulation, cladding or components, on a common basis. It also encourages teams to consider durability and material choices early. Guidance from WRAP adds that whole life costing can reveal procurement costs, including maintenance and environmental impacts, that are overlooked when only the upfront price is considered.
For external works, the same reasoning applies to surface and finish selection. Material choice affects upkeep intervals and replacement cycles, and a discussion of long-term value in paver and surface materials illustrates how durability weighs against initial price. The principle carries over to façades, roofing, flooring and mechanical plant.
Three categories of decision most often benefit from LCCA in Singapore projects:
- Building envelope: glazing, cladding and waterproofing, where maintenance access and inspection cycles carry material cost.
- Mechanical and electrical plant: chillers, pumps, lifts and lighting, where energy use and replacement timing dominate.
- Retain, upgrade or redevelop: for older commercial stock, comparing a retrofit against a rebuild. The guide to upgrading an old commercial building for Green Mark sets out the technical side of that choice.
Singapore guidance and tools
The BCA reports that Green Mark buildings achieve energy and water savings that outweigh the early investment, and that Platinum-rated buildings take close to six years to recoup initial construction costs. Payback of this kind is a direct output of LCCA, since it shows how long an incremental cost takes to be recovered.
Green Mark 2021, in its second edition effective 1 January 2024, places greater emphasis on reducing embodied carbon across a building’s life cycle and provides a Whole Life Carbon technical guide. BCA’s Singapore Building Carbon Calculator includes a Building Embodied Carbon Calculator and a Mechanical & Electrical Carbon Calculator. Where carbon is priced or reported, these tools supply inputs for a whole life analysis. Owners seeking certification can refer to the Green Mark certification guide and the overview of Singapore building certification requirements.
For solar installations, the National Solar Repository’s LCC calculator estimates building-integrated photovoltaic (BIPV) life cycle cost, accounting for electricity bill savings and environmental implications on generalised energy efficiency assumptions. Because those assumptions are generic, project-level inputs should replace them in a final appraisal. Industrial owners on JTC land should also review the JTC solar deployment requirements before modelling.
Handling uncertainty in the estimate
Every LCCA rests on forecasts of energy tariffs, maintenance behaviour, component lives and the discount rate. The US Federal Highway Administration’s LCCA primer distinguishes deterministic analysis, which uses single-value inputs, from probabilistic analysis, which models the variability of inputs. It describes sensitivity analysis as changing one input, such as the discount rate or initial cost, across its plausible range while holding the others constant, which shows the variables that influence the result most. The same primer notes that real discount rates in such analyses typically range from 3 to 5 percent.
A defensible report for a Singapore project therefore does the following:
- States the base-case assumptions and their sources, such as the BCA’s 30-year period and 5% rate.
- Re-runs the comparison at lower and higher discount rates and over shorter and longer study periods.
- Identifies the break-even point: the discount rate or cost level at which the ranking of options changes.
- Reports the ranking as robust only if it holds across the tested range.
- Documents what is excluded, such as user costs or externalities, so that the reader knows the boundary of the result.
In the worked example above, Option B remains ahead at any discount rate up to a level where the annual saving no longer repays the extra S$150,000 within the study period. Showing that threshold is more useful to a board or lender than a single figure.
Where the analysis fits in the project programme
The BCA’s own guidance places LCCA in early design, and that timing governs its value. After the structural system, façade and plant are fixed, the options that remain are narrow. Early project planning should therefore reserve a stage for option appraisal, with the cost plan and the engineering design developed together. Digital models strengthen the exercise: 3D BIM supports quantity extraction and coordination across disciplines, and the guide to BIM for Singapore developers describes how those models support cost and planning decisions. Investors who need a market view of the resulting asset can consult the building valuation guide for developers and investors.
Our perspective
Life cycle cost is rarely settled by one discipline. The façade, the mechanical plant, the structure and the statutory inspection cycle each contribute to the long-term cost profile, and an analysis that separates them tends to misstate the total.
Our approach is to bring structural, façade, mechanical and electrical engineering, quantity surveying and authority submissions into one view. Aman Engineering Consultancy offers value engineering, feasibility studies and quantity surveying, and handles statutory submissions across BCA, URA, JTC, HDB, SCDF, PUB and LTA. Option appraisal on that basis reflects the approvals, inspections and certifications that a building will actually carry, not only the construction budget.
We recommend that owners fix the study period, discount rate and cost boundary at concept stage, document them, and test the result against a range of assumptions. A transparent analysis allows a developer, lender or agency to see why one option was selected.
Aman
Commissioning a life cycle cost analysis
An LCCA is most reliable when the same team that prices the options also understands the engineering and the statutory obligations attached to each. Aman Engineering Consultancy provides Value Engineering to compare design and system alternatives, Feasibility Studies for project-level appraisal, and Quantity Surveying Services for the cost data. Property developers, construction firms, building owners and government agencies can start from the Aman Engineering Consultancy site.
Engagements are project-based, and the scope follows the decision to be made: a single system comparison, a whole-building appraisal, or a retain-or-redevelop study.
FAQ
What is the difference between life cycle costing and whole life cost analysis?
Life cycle costing covers construction, operation, maintenance and disposal costs over a defined period. Whole life costing has a wider scope and can include client and user costs, income and external costs, as the RICS guidance explains. Some publications use the two terms synonymously, so the report should state which boundary it applies.
What study period and discount rate should a Singapore building use?
The BCA’s Green Mark consultancy study used a 30-year study period, a 5% discount rate and 1.5% annual escalation. These are suitable reference values. The study period should match the owner’s holding period or the design life of the main systems, and the discount rate should be tested across a range.
Which costs belong in the analysis?
Initial capital, operating, maintenance and replacement costs form the core, as in the BCA study. End-of-life costs or residual value are added for a full life cycle view. Recurring statutory inspections and rectification works belong in the maintenance line.
When should the analysis be done?
At concept and early design stage. The BCA states that applying LCCA early allows developers to choose among building and system designs. Later in the programme, the structure and major systems are fixed, and the analysis can only confirm decisions already made.
Sources
- Life cycle costing, RICS professional standard
- Life-Cycle Cost Assessment in Real Estate Decision-Making, Sustainability 2025
- The myth of costly green buildings, BCA
- The economics of green buildings: a life cycle cost analysis of non-residential buildings in Singapore, Bond University
- An introduction to whole life costing, WRAP
- Green Mark 2021, BCA
- LCC calculator, National Solar Repository of Singapore
- Life-Cycle Cost Analysis Primer, FHWA
- Driveway pavers and long-term value
Recommended
- Implementing Proactive Maintenance Strategies to Prolong Building Lifespan and Reduce Repair Costs in Singapore
- 5 Year vs 10 Year PSI Cycles: How Building Use Sets Your Inspection Deadline
- Periodic Facade Inspection for CBD Buildings in Singapore
- Singapore Owners: Up to $950k a Year from Design for Maintainability